Updraft helps people pay off credit card debt. It shows you every balance you owe and what that borrowing really costs, then replaces expensive card and overdraft balances with one fixed-rate loan, one fixed monthly repayment, and a finish date you get from day one. Updraft is a UK lender, authorised and regulated by the Financial Conduct Authority (firm reference number 810923), and it has passed £1bn in loans since its first loan in April 2019. Customers rate it 4.8 out of 5 on Trustpilot.
Card debt rarely ends with a bang. It drifts: several cards, each with its own rate and its own due date, minimum payments that barely reduce the balance, an overdraft on top, and no point at which anything feels finished. Updraft replaces that open-ended drift with something you can see the end of. One fixed-rate loan pays off your card and overdraft balances together, leaving one fixed monthly repayment on one due date, a finish date from day one, and tools in the app to try to beat it. If you want to pay extra some months, there are no fees for that; if you want to settle the loan in full early, there are no fees for that either, and the app shows your settlement figure whenever you ask it. And "faster" has one precise meaning here: paying off your cards sooner than you would by paying only the minimum.
Loans run from £1,000 to £25,000 over 2 to 5 years, with rates from 15.3% to 41.2% APR, subject to status and affordability. The interest rate is fixed for the full term, interest is charged daily, and an upfront fee is added to the loan, so there is nothing to pay out of pocket to get started. The loan is unsecured, so no home or other asset is needed. Every applicant sees a personal rate before accepting anything, and when the loan pays out you have a choice: Updraft can pay your card providers direct, or pay the money into your current account.
Representative example: 25.9% APR Representative based on a £10,000 loan over 60 months at 20.40% fixed interest p.a. Monthly repayment £283.20. Total repayable £16,992 (inc. £600 fee). Subject to status and affordability. Consolidating debt may increase the term and total amount repaid.
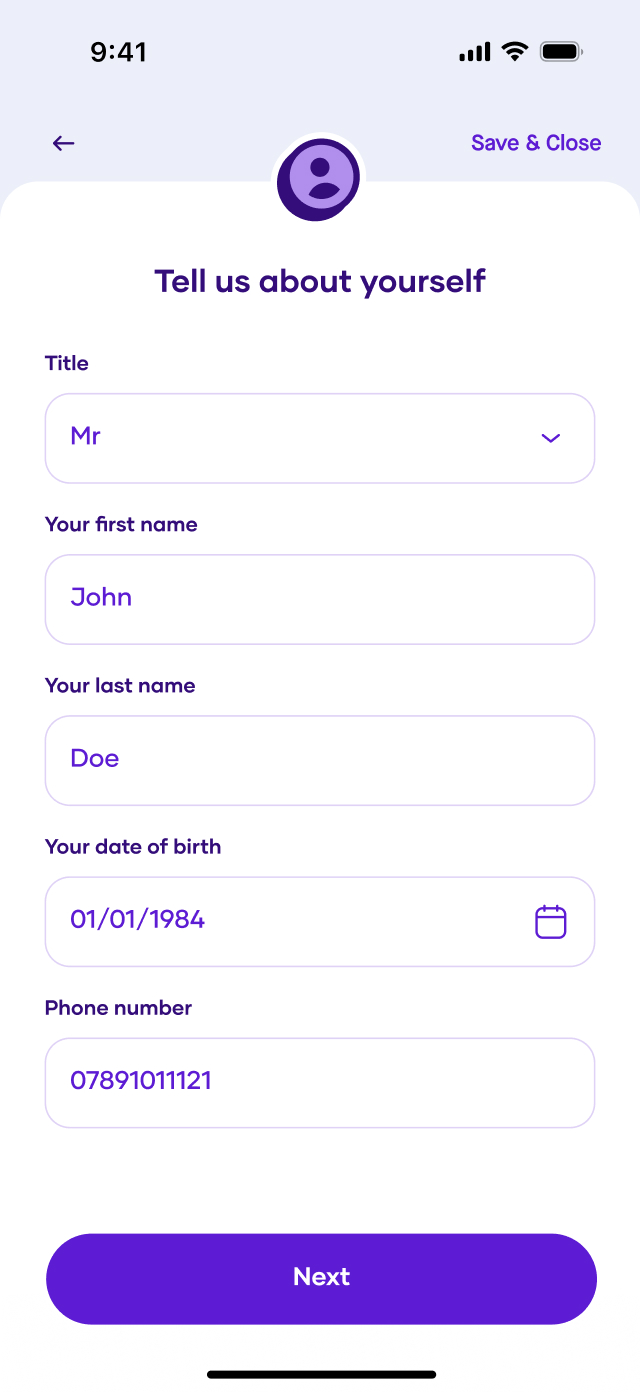
Updraft works in three steps: see what you owe, see what it is costing you, pay it off faster. It starts with an eligibility check that is a soft search, so it does not affect your credit score and other lenders cannot see it. From the first step you are finding out, not committing.
The full application includes an affordability check, and a hard search, run through TransUnion, happens only if you accept a loan offer, never before. Sharing bank data through open banking is optional: it runs through TrueLayer, an FCA-authorised provider, with read-only access, so Updraft can see income and spending but cannot move your money. For the complete walkthrough, see how it works from start to finish.
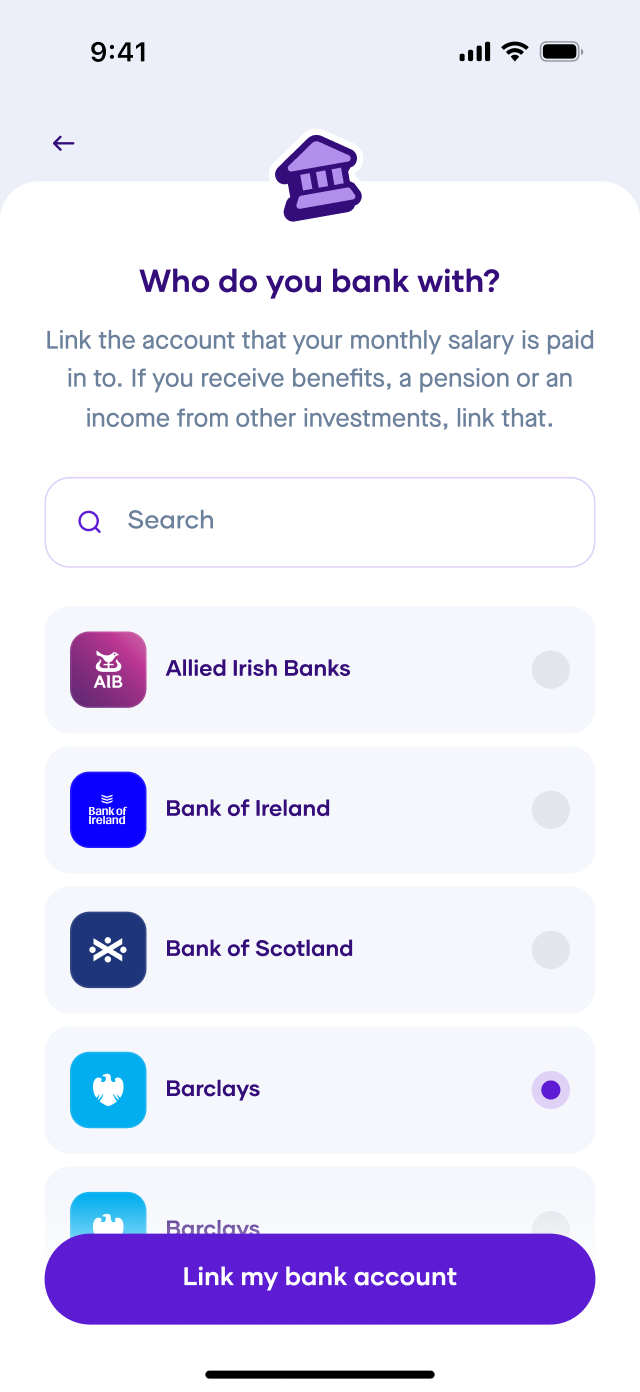
A credit file says where you have been. Open banking, shared with your permission, shows where you are. By looking at income and spending rather than the credit file alone, Updraft can assess what you can actually afford, and that matters most if your bank has turned you down for a consolidation loan. Every loan remains subject to status and affordability, but the assessment starts from a fuller, fairer picture of your finances.
The loan is the heart of the offer, and it is optional. Connect your accounts in the Updraft app and you can see every balance and what it really costs, then decide what to do next with clear numbers in front of you. No loan is needed just to look.
Updraft also publishes research on UK credit card debt from its own applicant data, including regional debt research, and the MoneyTalk blog covers practical money topics from the team, including Risk and Lending Strategy Advisor Kevin Allen writing on open banking in UK lending. To see the numbers behind the national card debt picture, explore our insights, or settle in with the MoneyTalk blog.
Updraft is built for people in the UK who carry balances on more than one credit card, often with an overdraft as well, and who want one fixed monthly repayment and a clear finish date. Many customers work full time, rent their home, and have young children. In the 12 months to September 2026, Updraft applicants brought a median card balance of £3,721 across about six cards, five of them active. Those figures describe Updraft applicants, not the UK population, but they show exactly who the product is shaped around. Most arrive with a familiar set of problems:
Updraft is the trading name of Fairscore Ltd, company number 10868865, registered in England, authorised and regulated by the Financial Conduct Authority with firm reference number 810923, and anyone can verify this on the FCA register. Updraft is a lender, not a broker and not a budgeting tool: it makes the loan itself, and you manage it in the app. If something goes wrong, you complain to Updraft first, and if you receive no final response within eight weeks, or you are unhappy with the response, you can take the complaint to the Financial Ombudsman Service.
The growth tells its own story. Updraft has passed £1bn in loans to help people pay off expensive credit card debt, a figure that counts opening loan balances since April 2019, including the upfront fee. The first £500m took over six years to reach; the second took about 17 months, and lending from January to September 2026 was 92.6% higher than in the same months of 2025. Behind the numbers sits a team that knows card debt from the inside: founder and CEO Aseem Munshi was Head of Cards and Unsecured Lending at HSBC UK, and Chief Risk Officer Micha Panagiotidi leads the risk discipline behind every loan.
Updraft ran its first national TV campaign in December 2025, and the industry noticed. So did customers, who rate Updraft 4.8 out of 5, "Excellent", from 6,348 reviews on Trustpilot: read the reviews on Trustpilot.
Honesty is part of the service. A new loan is not the answer for everyone, and if you cannot afford your current repayments, free, confidential debt advice is available from MoneyHelper, StepChange, National Debtline, or Citizens Advice. Talking to them costs nothing and commits you to nothing.
To apply, you need to meet a few simple requirements:
You can apply on the website and manage your loan in the Updraft app. The first step is a soft search: it does not affect your credit score, and other lenders cannot see it. When you are ready, start with a soft search and put a finish date on your card debt.